Introducing the Finance Toolkit MCP Server
On the 6th of May, 2023, Microsoft’s Price-to-Earnings ratio was reported as 28.93 by Stockopedia, 32.05 by Morningstar, 32.66 by Macrotrends, 33.67 by the Wall Street Journal, and 34.4 by Companies Market Cap. Every one of those numbers is “correct.” They just use different definitions of earnings, different share counts, and different rounding. None of the providers publish the formula, so there is no way to know which one matches the calculation you actually want.
That inconsistency is why I built the Finance Toolkit: an open-source Python library where every ratio, indicator, and model is implemented in plain, readable code you can audit yourself. It covers 500+ methods across equities, options, currencies, crypto, ETFs, indices, and macroeconomic data going back over a century, all sourced from 30+ years of financial statements. On top of the library sits an MCP server that exposes the same 500+ methods to any AI assistant that supports the Model Context Protocol, so you (or your assistant) never have to choose between writing Python and asking a question in plain English.
The source code for every calculation is on GitHub. The full documentation lives on the Finance Toolkit MCP server page.
Setting Things Up
The Python library and the MCP server are the same engine with two different front doors. Start with the Python side, since understanding it makes the MCP tool calls easier to reason about later.
First, install the Finance Toolkit:
pip install financetoolkit -U
Then import the library and create a Toolkit instance. Each section below swaps in a different ticker universe, since the point is showing the breadth of what one consistent API can pull, but the syntax never changes.
from financetoolkit import Toolkit

companies = Toolkit(
    tickers=["MSFT", "AAPL"],
    api_key="FINANCIAL_MODELING_PREP_KEY",
    start_date="2020-01-01"
)
Get your FMP API key at jeroenbouma.com/fmp. The free plan covers five years of history and 250 requests a day; a paid plan adds the full 30+ years and quarterly data, at a 15% discount through that (affiliate) link. You can also use your own data instead, as explained here.
From Code to Conversation: the MCP Server
Writing Python is not always the fastest way to get an answer, and getting an AI assistant to reason accurately over financial data by itself usually falls short: web search is unreliable, scraped data is inconsistent across sources (see the PE example above), and models hallucinate numbers when they cannot find them. The Finance Toolkit MCP server fixes this by giving any MCP-compatible assistant direct, structured access to the same 500+ methods, backed by the transparent calculation methods in the library.
You do not need a local Python environment to use it. A single command configures your AI client automatically:
uvx --from "financetoolkit[mcp]" financetoolkit-mcp-setup
This supports Claude Desktop, Claude Code, GitHub Copilot in VS Code, Cursor, Windsurf, and Gemini. If you use Claude Desktop specifically, there is also a one-click MCPB bundle on the latest GitHub release that skips the terminal entirely. Either way, you will be asked for the same FMP API key used above, and the free plan is enough to get started.
Once it is running, the server groups the 500+ Finance Toolkit methods into 22 categorical tools. You never name a function or set a parameter yourself; the assistant picks the right tool from your question and returns structured output. The depth of interpretation scales with the model: Claude Sonnet layers in qualitative reasoning on top of the numbers, while smaller models like GPT-5 mini return clean structured data without the narrative. Both work, since the server is built to support either.
Once set up, it looks like this in Claude Desktop.
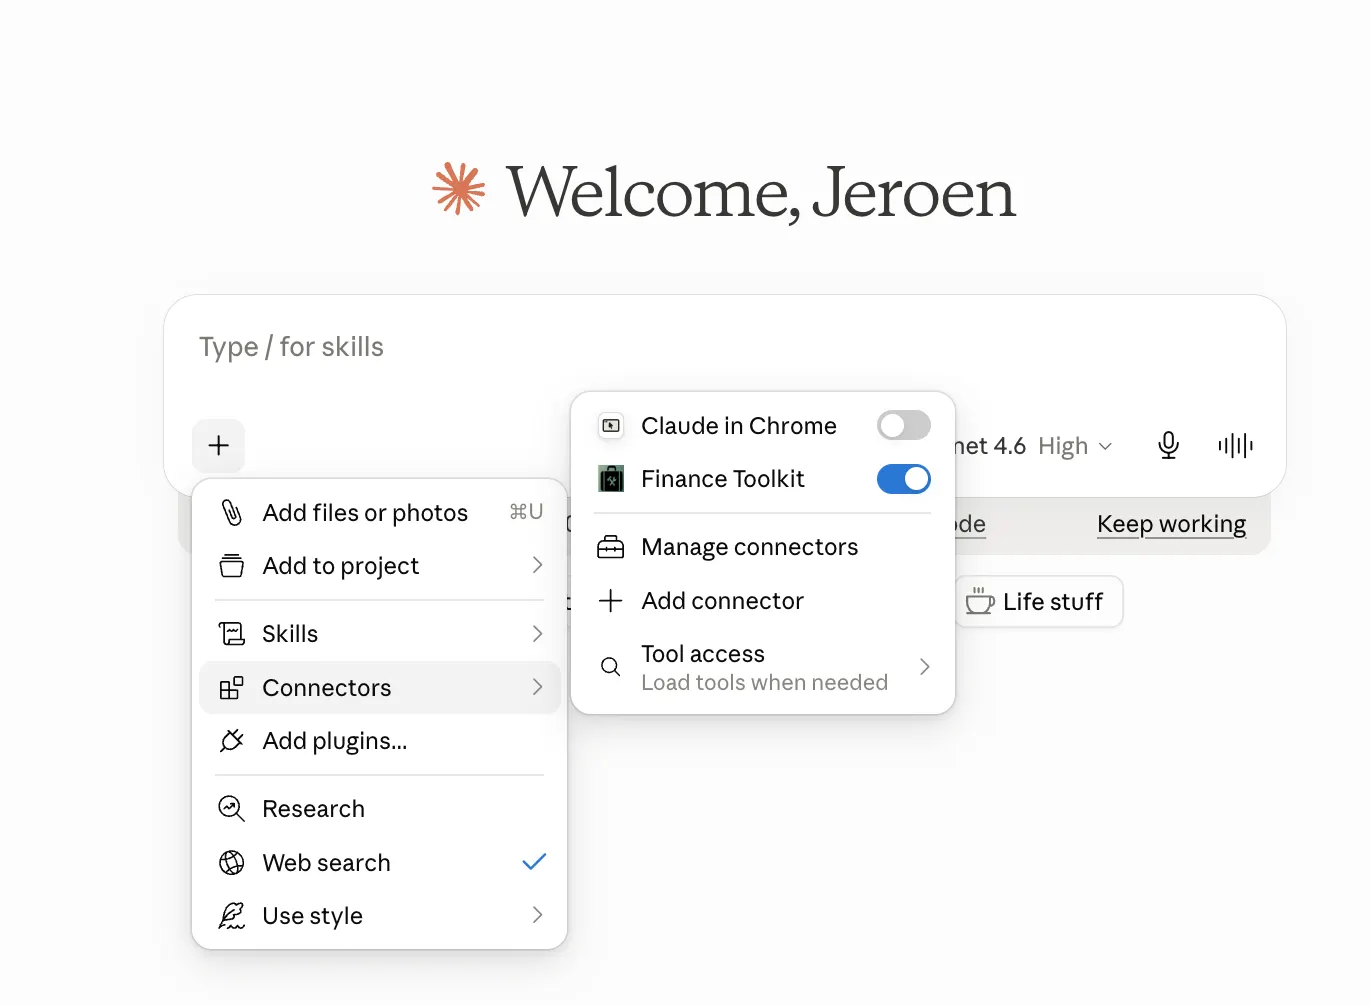
Once everything is set up, you should see the Finance Toolkit as one of the available connectors.
Equity Analysis: Margins, Returns, and Multiples Side by Side
The Finance Toolkit was built with equity research first, which is why this is the deepest category: profitability, valuation, efficiency, liquidity, and solvency ratios, plus models like WACC, DuPont decomposition, the Altman Z-Score, and the Piotroski F-Score. A good stress test for any of these is an industry where growth rates differ wildly between names that are nominally in the same business: semiconductors.
from financetoolkit import Toolkit

chips = Toolkit(
    tickers=["NVDA", "AMD", "ASML", "TSM", "AVGO", "INTC", "QCOM", "TXN", "AMAT"],
    api_key="FINANCIAL_MODELING_PREP_KEY",
    start_date="2015-01-01"
)

cumulative_return = chips.get_historical_data()
pe = chips.ratios.get_price_to_earnings_ratio()["2025"]
ev_ebitda = chips.ratios.get_ev_to_ebitda_ratio()["2025"]
eps_growth = chips.ratios.get_earnings_per_share(growth=True)["2025"]
revenue_per_share = chips.ratios.get_revenue_per_share()["2025"]
Which returns:
| Ticker | Cumulative Return (2015-2025) | P/E (2025) | EV/EBITDA (2025) | EPS Growth (2025) | Revenue/Share (2025) |
|---|---|---|---|---|---|
| NVDA | +42,215% | 63.5x | 55.5x | +146.2% | $5.26 |
| AMD | +20,344% | 80.8x | 52.2x | +164.3% | $21.17 |
| AVGO | +3,935% | 72.6x | 50.5x | +286.2% | $13.16 |
| AMAT | +2,347% | 29.7x | 23.8x | +0.6% | $35.11 |
| TSM | +1,981% | 28.4x | 18.0x | +57.2% | $23.75 |
| ASML | +1,762% | 36.9x | 28.0x | +45.0% | $98.67 |
| QCOM | +297% | 34.1x | 14.2x | -44.1% | $40.08 |
| TXN | +585% | 31.9x | 21.3x | +4.8% | $19.37 |
| INTC | +352% | - | 19.1x | -98.75% | $10.88 |
What stands out is the dispersion inside one industry. NVDA turned a 2015 position into roughly 421 times its starting value, while INTC is (compared to NVDA) essentially flat a decade later, its P/E reported as negative because it posted a net loss and its EPS collapsing 98.75% in 2025 alone. AVGO’s EPS growth of 286.2% outpaces even NVDA, reflecting the VMware acquisition layered on top of its AI networking business rather than organic chip sales growth, worth separating out before reading too much into the headline number. ASML trades at the richest EV/EBITDA multiple in the group (28.0x) despite the slowest revenue-per-share base of the bunch in absolute growth terms, a premium the market assigns to its effective monopoly on the EUV lithography machines every leading-edge fab depends on.
Asking the Finance Toolkit MCP the same question returns an answer like the one below.
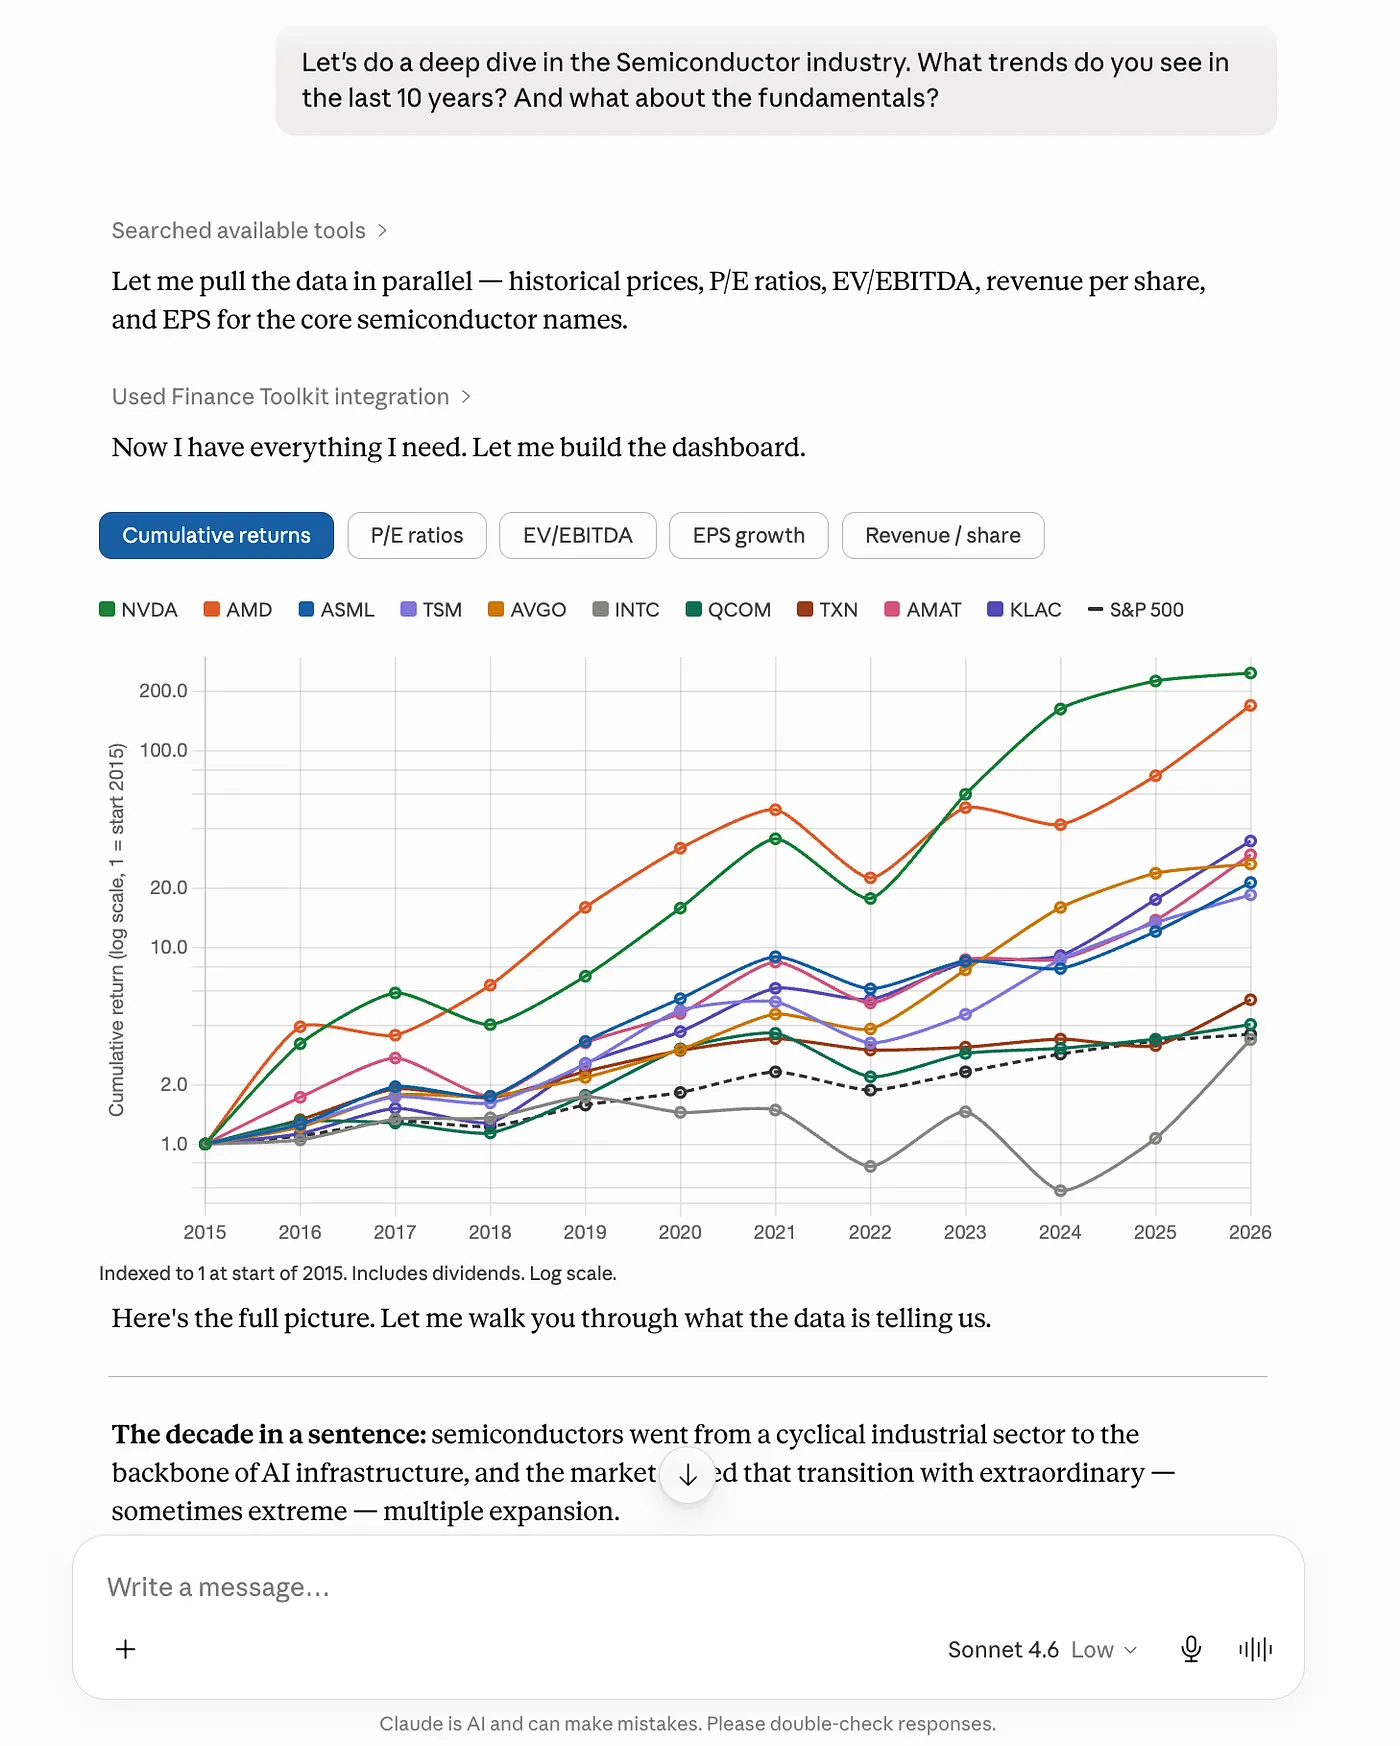
Over the last decade semiconductors went from a cyclical industrial sector to the backbone of AI infrastructure, and the market priced that transition in. NVDA and AMD returned over 150x since 2015, while the S&P 500 sits at the bottom of the same chart.
Technical Analysis: Is the Market Overbought?
Technical indicators work off OHLC price data, so they apply to any asset class the Toolkit supports, not just equities. RSI, MACD, the Stochastic Oscillator, and Bollinger Bands are all available, grouped under categories like momentum, volatility, and overlap. The clearest stress test for a momentum indicator is a market shock, so this one looks at European sector ETFs through the 2020 Corona crash and the year that followed.
from financetoolkit import Toolkit

sectors = Toolkit(
    tickers=["EXV9.DE", "EXV1.DE", "EXV4.DE", "EXI5.DE", "EXV3.DE", "EXH9.DE", "EXH1.DE"],
    api_key="FINANCIAL_MODELING_PREP_KEY",
    start_date="2019-11-01"
)
rsi = sectors.technicals.get_relative_strength_index(period="monthly")
These are iShares STOXX Europe 600 sector UCITS ETFs: EXV9.DE (Travel & Leisure), EXV1.DE (Banks), EXV4.DE (Health Care), EXI5.DE (Real Estate), EXV3.DE (Technology), EXH9.DE (Utilities), and EXH1.DE (Oil & Gas).
Which returns:
Oil & Gas was the most oversold sector of the whole crisis, bottoming at an RSI of 19.3 in September 2020, well past the typical oversold line of 30, and it stayed depressed there for most of the year as travel demand collapse fed straight through to fuel demand. Banks were close behind, troughing at 26.2 in June 2020 and not climbing back above the 40 mark until November, longer than any other sector here took to recover. Health Care and Technology never came close to oversold even at the worst of the March 2020 crash, with RSI bottoming at 65.9 and 53.2 respectively, the closest thing to a flight-to-quality signal in this dataset.
The reversal is more interesting. The same two sectors that bottomed hardest, Oil & Gas and Banks, both closed 2021 deep in overbought territory at 76.3 and 79.5, a swing of roughly 50 to 60 RSI points in eighteen months. That is the kind of regime change a single point-in-time RSI reading would never catch; it only shows up when you pull the full series.
The Finance Toolkit MCP shows the same pattern when you ask it:
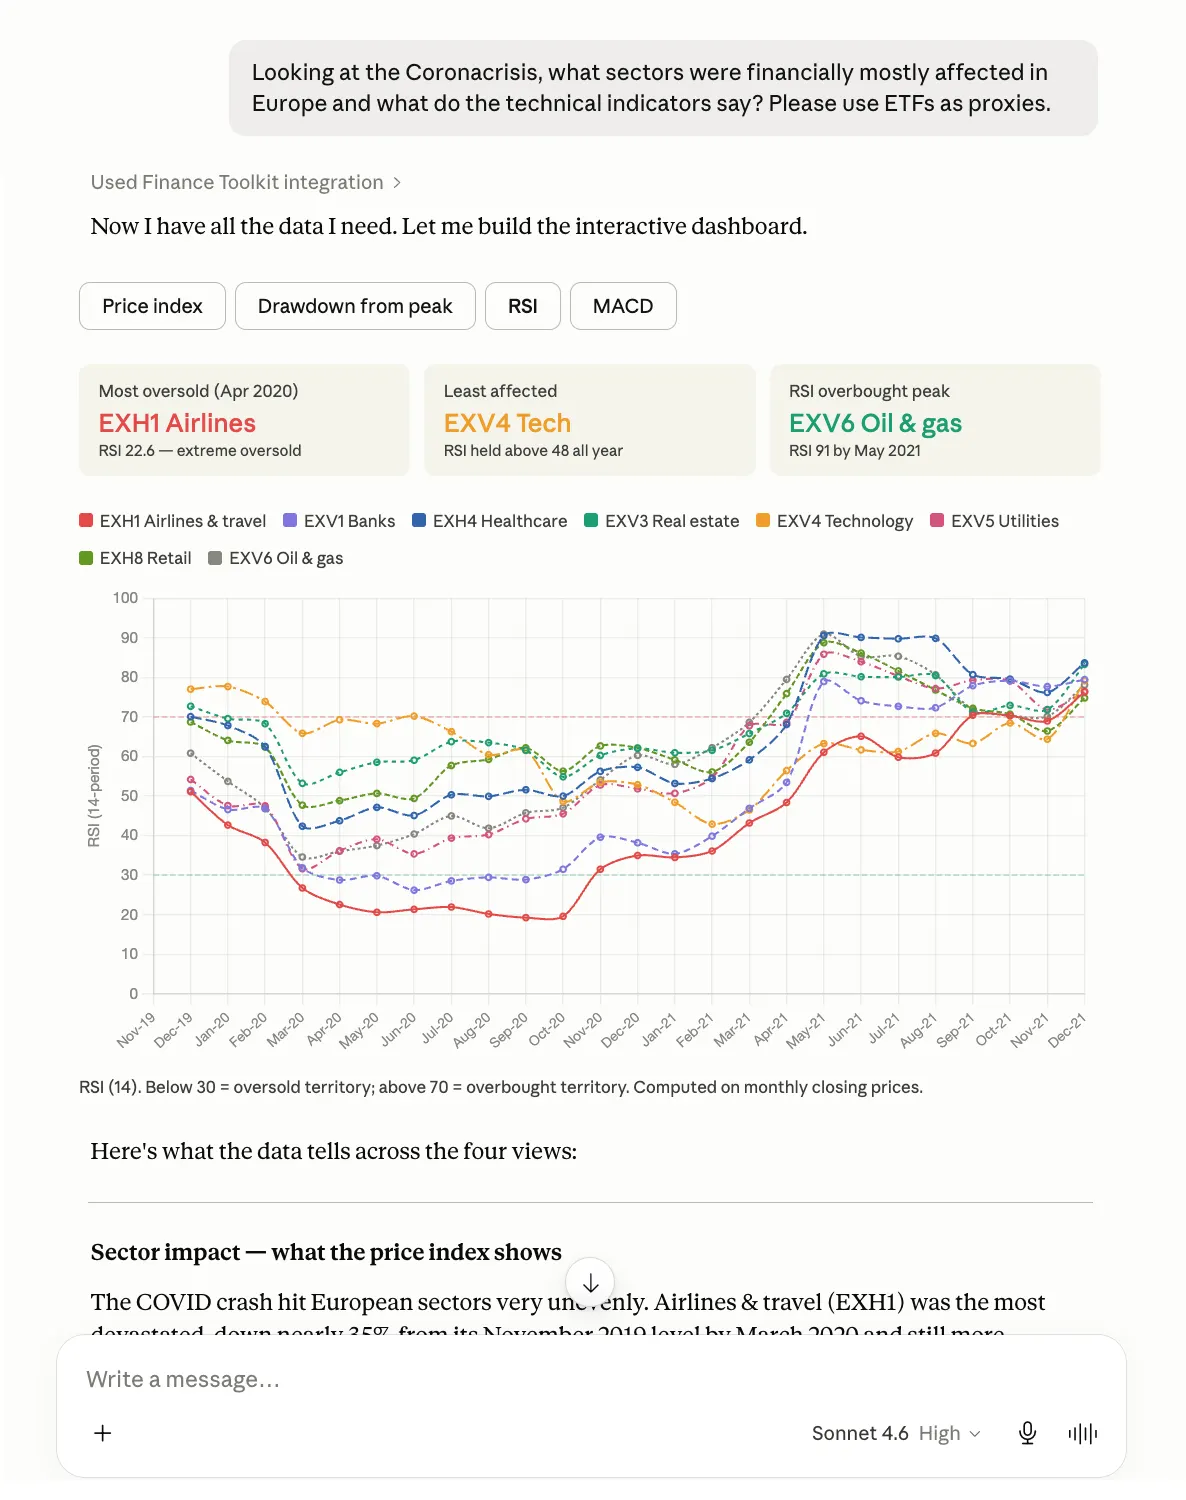
The COVID crash was swift but uneven. Oil & Gas (EXH1, mislabelled "Airlines & travel" in this chart) fell into extreme oversold territory, with an RSI of about 22 in April 2020 and below 20 by the autumn, levels that signal panic selling rather than a fundamental repricing. Technology barely dipped. Basic Resources (EXV6, labelled "Oil & gas" in the chart) swung to an RSI of 91 by May 2021 as the commodity cycle turned. Always check the tickers an AI assistant puts on a chart.
Risk and Performance: What the Fama-French Factors Reveal About South American Stocks
Beta and alpha alone treat “the market” as the only systematic risk that matters. The Fama-French five-factor model goes further, decomposing returns into exposure to the market (Mkt-RF), company size (SMB), value versus growth (HML), profitability (RMW), and investment intensity (CMA), plus an R-squared that tells you how much of the return that combination actually explains. South American equities are a good test case, since they mix commodity exporters, banks, and a tech name that behaves nothing like the rest of the region.
from financetoolkit import Toolkit

south_america = Toolkit(
    tickers=["PBR", "YPF", "VALE", "SCCO", "ITUB", "CIB", "MELI", "GGB"],
    api_key="FINANCIAL_MODELING_PREP_KEY",
    start_date="2021-01-01"
)
fama_french = south_america.performance.get_fama_and_french_model(period="yearly")
Which returns, for 2025:
| Ticker | Mkt-RF | SMB | HML | RMW | CMA | R² |
|---|---|---|---|---|---|---|
| ITUB (Itau, bank) | 0.0167 | -0.0023 | -0.0071 | -0.0116 | -0.0051 | 0.683 |
| SCCO (Southern Copper, mining) | 0.0146 | 0.0000 | -0.0047 | -0.0117 | -0.0033 | 0.529 |
| VALE (Vale, mining) | 0.0118 | 0.0042 | -0.0086 | 0.0032 | -0.0103 | 0.511 |
| CIB (Bancolombia, bank) | 0.0109 | -0.0029 | 0.0024 | -0.0107 | -0.0101 | 0.340 |
| MELI (MercadoLibre, e-commerce) | 0.0087 | -0.0001 | -0.0005 | -0.0023 | -0.0049 | 0.122 |
| YPF (YPF, energy) | 0.0067 | 0.0023 | -0.0027 | -0.0041 | -0.0008 | 0.192 |
| GGB (Gerdau, steel) | 0.0063 | -0.0029 | -0.0014 | -0.0110 | -0.0009 | 0.276 |
| PBR (Petrobras, energy) | 0.0057 | -0.0017 | 0.0002 | -0.0037 | 0.0009 | 0.169 |
The R-squared column is the most useful read here, since it tells you how reliable the rest of the row is. ITUB’s 2025 regression explains 68.3% of its return variance through these five factors, the highest in the group and typical of a large, liquid bank whose returns track broad risk factors closely. MELI sits at the other extreme: only 12.2% of its return is explained by the model, which fits a company whose price action is driven far more by idiosyncratic growth narrative and earnings surprises than by size, value, or investment-style exposures.
That gap widens when you look at the trend across years rather than a single snapshot:
MELI’s R-squared has fallen almost every year since 2021, from 0.619 to 0.122, meaning the five-factor model explains less and less of its return over time as the stock has decoupled further from traditional risk factors. VALE and SCCO show the opposite pattern, with explanatory power roughly tripling over the same five years as both mining names became more tightly linked to broad market and value-style risk during the commodity cycle. None of that shows up in a beta or alpha calculation alone, which is the case for running the full factor model instead of stopping at single-factor CAPM.
Through the Finance Toolkit MCP, the answer looks like this.
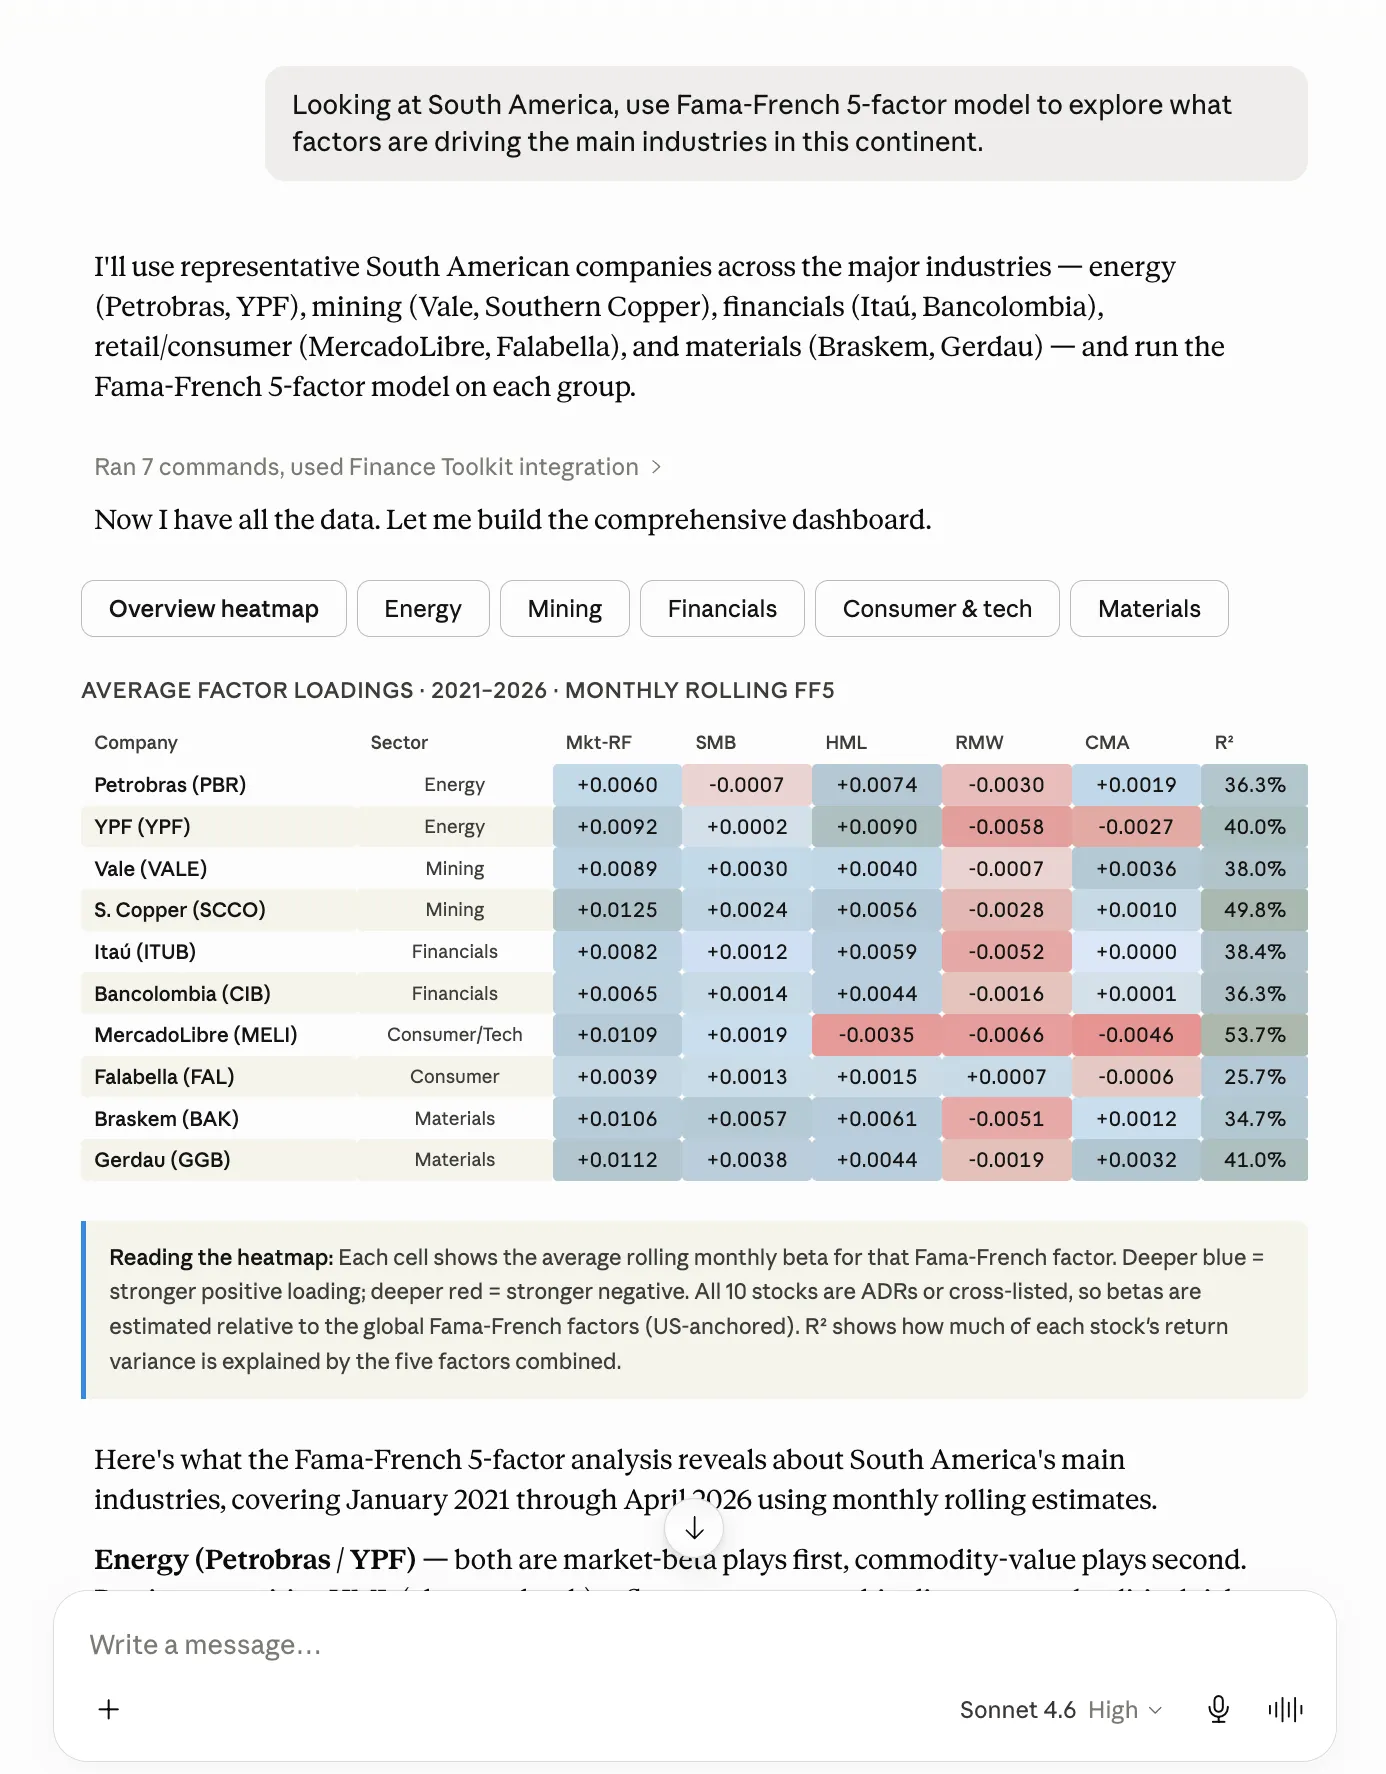
The Fama-French 5-factor model decomposes stock returns into market beta, size, value, profitability, and investment exposure. Applied to South American industries, it shows that MercadoLibre behaves more like a US growth stock than a Latin American consumer play, while energy names like Petrobras and YPF are primarily market-beta bets with a secondary value tilt.
Macroeconomic Analysis: Tracking Asia’s Growth Engines
Macroeconomic data goes back over a century and covers 60+ countries: unemployment, GDP growth, inflation, trade balances, government debt, central bank rates, and government bond yields, sourced from the OECD and the Global Macro Database. It is available through the economics module on a Toolkit instance, or as a fully standalone module if you only need macro data.
from financetoolkit import Economics

economics = Economics(start_date="2020-01-01")

gdp_growth = economics.get_gross_domestic_product(
    countries=["India", "Vietnam", "Indonesia", "China", "South Korea"],
    growth=True
)
Which returns:
India has held growth above 9.5% every year since the 2020 contraction, while China has settled into a slower mid-single-digit pace after its 2021 reopening spike. South Korea, the most mature economy in this group, tracks closest to developed-market growth rates throughout. None of this required scraping a single government website or reconciling conflicting definitions across sources, which is the same problem this whole project started from.
Asking the Finance Toolkit MCP gives an answer like the one below.
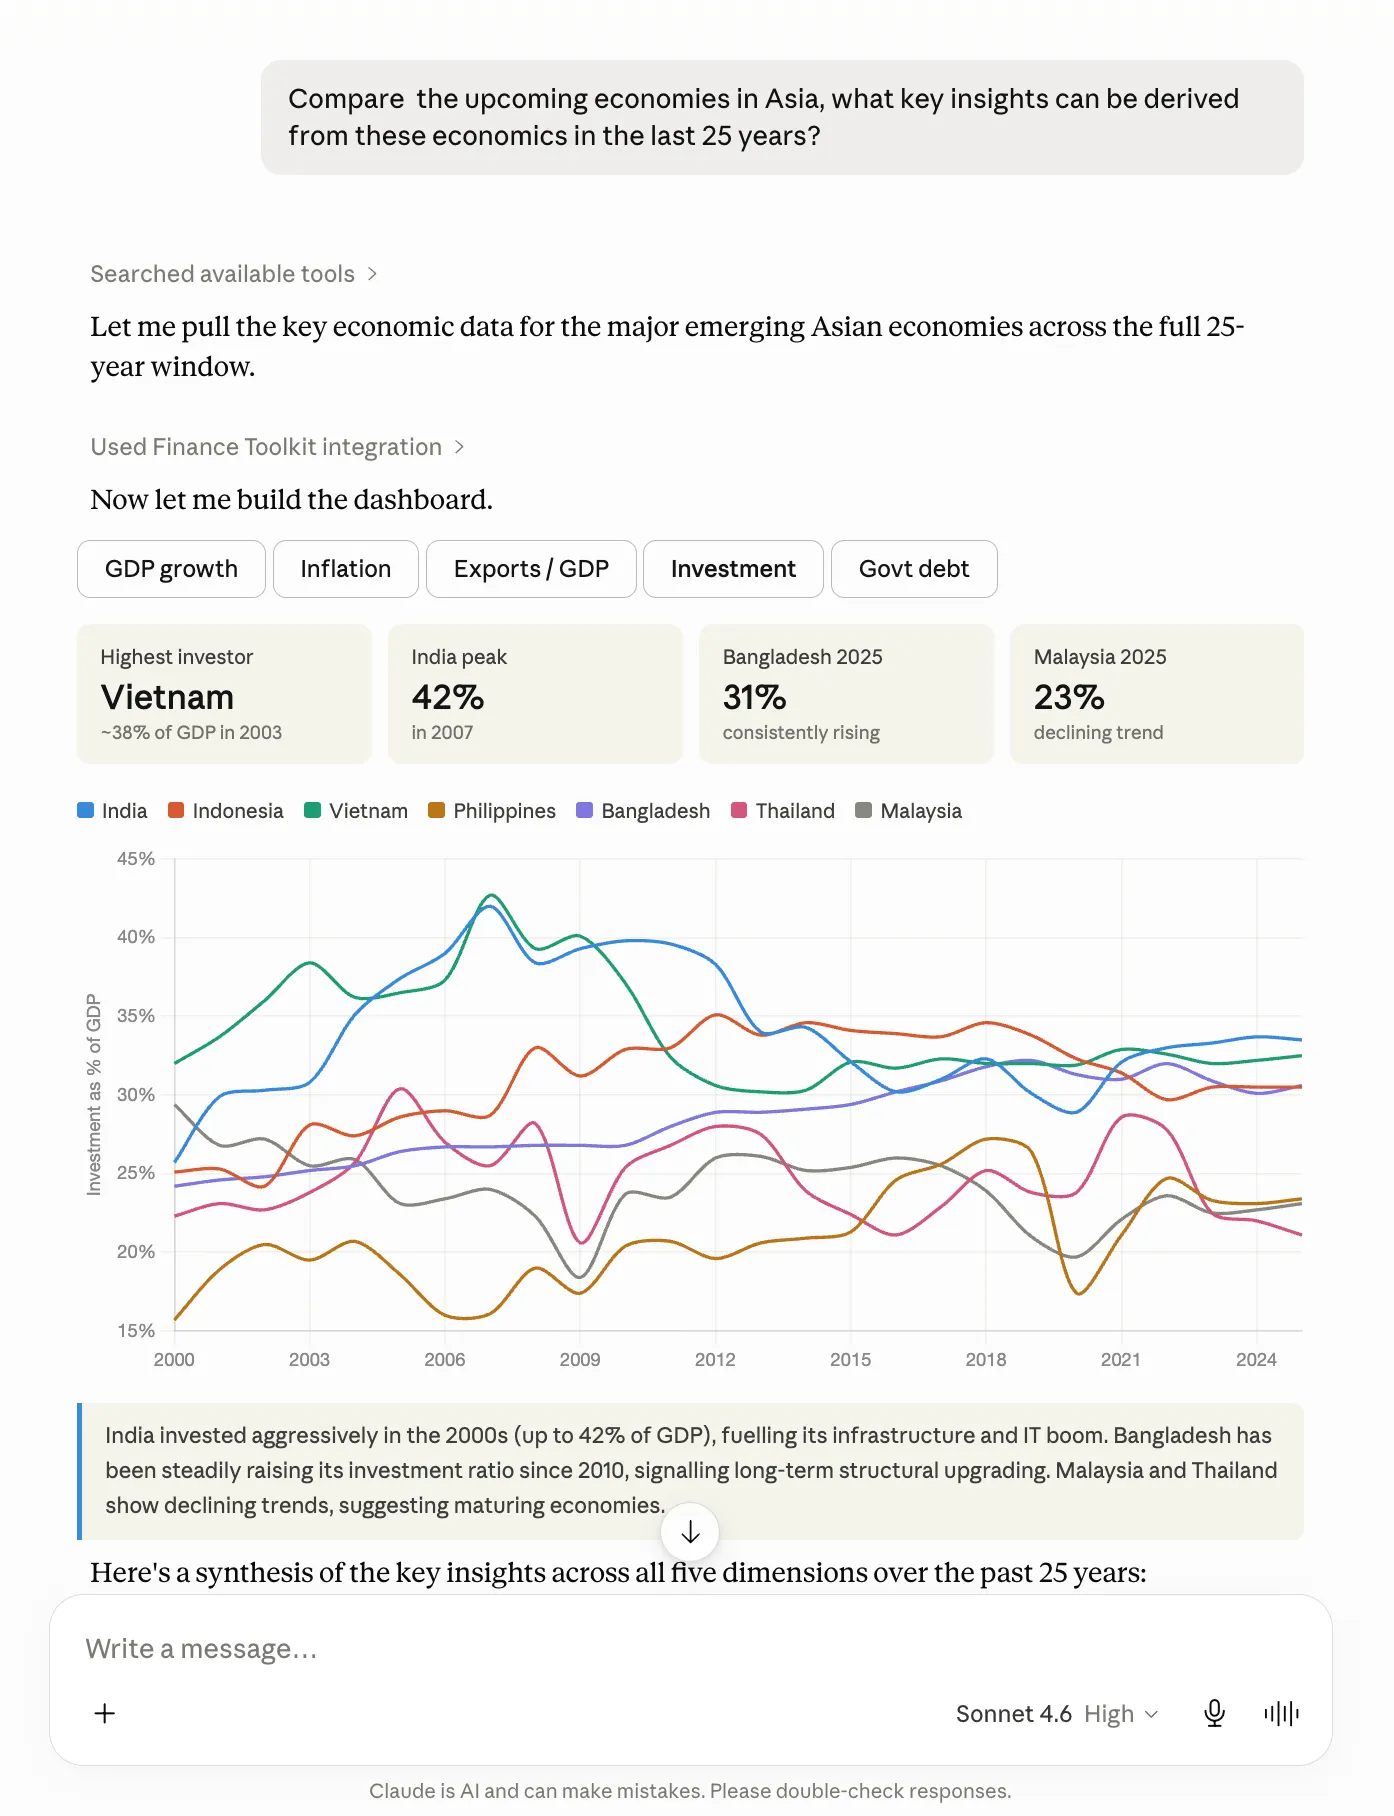
Investment as a share of GDP is one of the cleanest leading indicators of structural economic development. Vietnam and India led the region in the 2000s, fuelling their infrastructure and manufacturing buildouts. Bangladesh has been rising steadily since 2010, which is typical of an economy still in the upgrading phase rather than one that has plateaued like Malaysia or Thailand.